- Hawook: Your Southeast Asia Property Insider
- Posts
- Vietnam bonds hit 13.5%: the SE Asia debt crunch nobody is pricing
Vietnam bonds hit 13.5%: the SE Asia debt crunch nobody is pricing
Capital costs are spiking, inventory is compressing, and the gap between the right deal and the wrong one just got much wider.

Maya Chen
October 06, 2026

Southeast Asia Property Intelligence
The Hawook Weekly
Tuesday, October 6, 2026
The capital markets are tightening. The deal flow is bifurcating. Here is what it means for your portfolio this week.
Got a deal to run past us? Message us on WhatsApp or fill out our quick form. No spam, just signal.
Main Story
🏗️ The Debt Wall Has Arrived: Vietnam Bonds Spike to 13.5% as Thailand Faces a 150 Billion Baht Maturity Crunch
Something structural is happening in Southeast Asian real estate finance, and it is not good news for anyone holding a leveraged developer position. Across two of the region's most active markets, the cost of capital is spiking to levels that are forcing developers into corner solutions, distressed pricing, and aggressive restructuring.
In Vietnam, real estate corporate bond issuance surged 147% year-on-year in the first eight months of 2026, reaching VND 20 trillion. That headline number would be encouraging if it reflected healthy capital demand. It does not. Developers are paying up sharply to raise this money: Khai Hoan Land is offering a 13.5% coupon, Tandoland is offering 12 to 13%. To put those numbers in context, these are sovereign bond territory coupons being attached to private, illiquid, development-stage real estate risk. Real estate firms now account for more than 70% of all delayed corporate debt obligations in Vietnam, which tells you how much of the 2024 and 2025 issuance wave has already gone sour.
Thailand's picture is different in mechanism but similar in outcome. The country is heading into a 150 billion THB bond maturity wall in 2026, while bank mortgage rejection rates hold at 40 to 50% for properties priced below 3 million THB. Developers have responded by cutting new launches to approximately 17,000 units for the full year, a 20-year low, and pivoting toward inventory clearance and Rent-to-Own structures to work through existing stock.
⚖️ Both sides of the crunch
Who gets hurt:
- Off-plan buyers in leveraged projects with developer bonds maturing before construction is complete
- Retail bond holders who reached for the 12 to 13.5% yield without reading the underlying developer balance sheets
- Mass-market domestic buyers in Thailand, locked out of mortgages by a 40 to 50% rejection rate
Who benefits:
- Cash buyers and institutional private debt funds, acquiring land banks and secondary stock at 10 to 20% discounts
- Foreign buyers in Thailand using hard currency, effectively insulated from domestic credit tightening
- Prime secondary market sellers, benefiting from reduced competition from new supply
The practical read for cross-border investors: audit the developer debt maturity schedule before committing to any off-plan purchase, and treat the current compression in Thai new supply as a medium-term tailwind for existing prime secondary listings. Vietnam's anticipated FTSE equity market upgrade could widen capital sourcing options for stronger property firms, potentially stabilising the sector by mid-2027. The weaker ones will not survive to see it.
🏖️ Now on Hawook App
Rhea by Sansiri | Surin Beach, Phuket
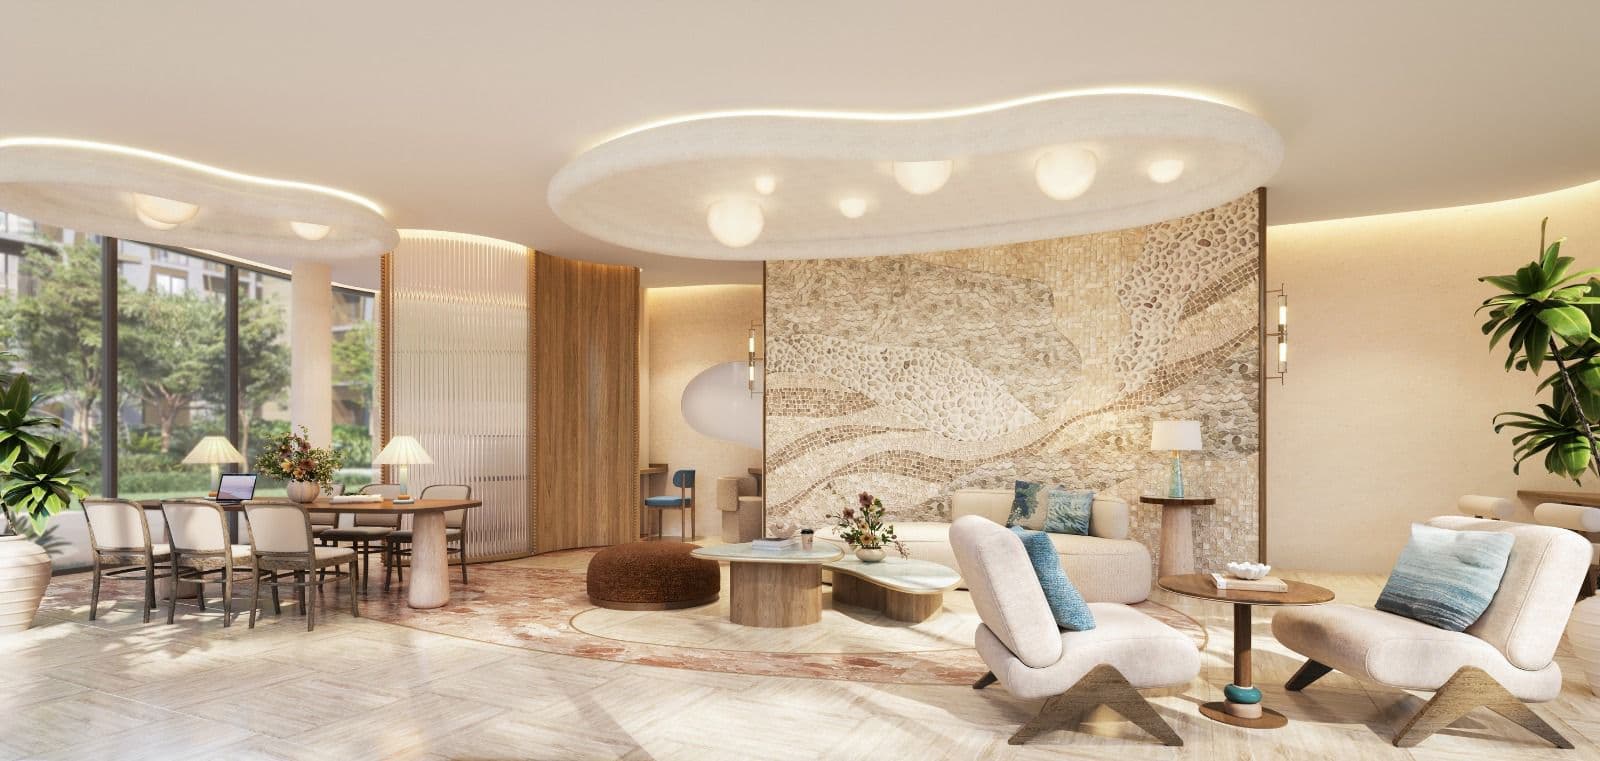
New residential supply in Surin is rare, and a Sansiri project within walking distance of the beach is rarer still. Rhea is three low-rise buildings, 295 units, built around a 900 sqm landscaped lagoon rather than the high-density resort formula common in Bang Tao. Fully fitted at handover (furniture, appliances, plus a year of PLUS Concierge) and genuinely pet-friendly with a dedicated pet park. Pricing starts from 3.99M THB on a Chanote title with an approved EIA. Honest trade-offs: no sea views due to the 23-metre west-coast height cap, handover in November 2027, and realistic net rental yield of 3.2 to 4.3% (not condotel numbers). Foreign quota is approximately 30% remaining. For lifestyle buyers and long-term residents who value location scarcity, one of the stronger Phuket picks this cycle.
View full analysis on the Hawook AppSecondary Story
🇸🇬 Singapore: Prices Hold, Volumes Drop, and the En Bloc Playbook Just Got Rewritten
Singapore's Q3 2026 residential flash data arrived this week and the headline tells a familiar story: prices are up, volumes are down. Private home prices rose 1.4% quarter-on-quarter, with suburban Outside Central Region property leading at 2.2%. The prime Core Central Region edged down 0.1%, a signal that high-net-worth buyer appetite is staying selective at current valuations. Overall transaction volumes fell 30% quarter-on-quarter to 4,296 units.
HDB resale moved in the opposite direction: prices dipped 0.2% but volume surged 17.7%, driven largely by the lifting of the 15-month wait-out period policy. Full-year private residential price growth is forecast at approximately 3%, per Savills Singapore. And Singapore's total investment sales forecast for 2026 has been revised upward to S$55 to S$60 billion, up S$15 to S$20 billion from earlier projections.
The bigger structural development is the Ministry of Law's update to the en bloc (collective sale) consent framework. Consent thresholds have been reduced from 80% to 70% for buildings aged 40 to 59 years, and to 65% for buildings aged 60 years or older. This is a significant unlocking mechanism for aging suburban strata developments and is likely to accelerate urban renewal activity in the OCR, precisely where price growth is already strongest. If you hold a unit in an older heartland block, it is worth checking where your development sits in the age bracket now.
📋 Singapore Q3 2026 Snapshot
- Overall private residential price index: +1.4% QoQ
- Outside Central Region (suburban): +2.2% QoQ
- Core Central Region (prime): -0.1% QoQ
- Private transaction volume: 4,296 units (-30% QoQ)
- HDB resale volume: +17.7% QoQ
- En bloc consent threshold (60+ year buildings): now 65%
- Full-year private price growth forecast: approximately 3%
Regional Market Update
🌏 Thailand and Indonesia: Where the Numbers Got Interesting This Week
🇹🇭 Thailand: Bangkok Condos Rebound Quietly While the Islands Go International
While the headline story in Thai real estate is supply compression and mortgage rejection rates, the Bangkok condominium segment is quietly putting up some of the strongest numbers seen in years. Q2 2026 condominium sales grew 19.5% year-on-year in Greater Bangkok, with value growth of 14.7%. Sukhumvit registered a monthly absorption rate of 5.2%, implying full inventory clearance in around 16 months. Compare that to low-rise housing, which faces a 67-month clearance horizon, and the picture becomes clear: transit-connected urban condominiums are the functioning part of the Thai property market right now.
On the resort market side, Koh Samui and Koh Phangan have crossed a significant threshold: foreign buyers now account for more than 90% of real estate acquisitions on both islands. These are no longer domestic holiday home markets with foreign interest. They are fully internationalised resort villa markets, which changes demand dynamics, pricing logic, and exit options for sellers. That is a very different buyer pool to underwrite against.
One regulatory item to watch: Thailand's Ministry of Commerce is running corporate audit sweeps targeting 125,622 entities suspected of using illegal nominee structures to bypass foreign land ownership limits. The compliance risk for anyone operating through nominee arrangements just went up materially.
🇮🇩 Indonesia: When Landed Homes Cost 22 Times Your Annual Income
Indonesia's affordability crisis in Jakarta is now quantified, and the number is stark. Landed residential valuations in Greater Jakarta have reached a median price-to-income multiple of 22 times household income, compared to 8.8 times for vertical condominium units. The result: 68% of Gen Z and Millennial buyers in Jakarta now view traditional home ownership as unfeasible, and are actively choosing co-living formats and transit-oriented apartments instead. This is not a temporary squeeze. It is a structural demand shift that will drive vertical residential development for at least the next decade.
Meanwhile, Jakarta CBD office rents are forecast to grow 2 to 3% in 2026, supported by high prime asset occupancy. For investors looking at Indonesia, the commercial and vertical residential story is where institutional capital is concentrating. Landed suburban housing is not the play right now.
💡 Personal Finance Hack
Vietnam's 13.5% Bond Yields: The Number Is Attractive. The Catch Is Not.
If you are holding cash in Southeast Asia while waiting for the right property deal, 12 to 13.5% corporate bond yields from Vietnamese real estate developers might look like a smart parking place. They are not, at least not without serious due diligence. Here is the framework for thinking about it before you wire anything.
🚩 The risk checklist (before you say yes):
- Real estate firms account for more than 70% of all delayed corporate debt in Vietnam right now. That is the risk pool you are joining.
- These are unlisted, illiquid instruments. There is no secondary market if you need to exit early or if your property deal closes sooner than expected.
- The coupon rate is the headline. Read the full repayment schedule, the collateral type, and whether the bond is secured against a specific project or a general balance sheet promise.
- A developer with a strong track record and audited financials is a different risk profile from a first-time issuer paying 13.5% because no bank will lend to them at that rate.
✅ What the alternatives actually look like:
- A fixed deposit at a reputable Thai or Singapore bank returns 2 to 4% with full liquidity and no credit risk. It is not exciting. That is the point.
- For Vietnam exposure specifically, equity in a properly regulated fund with diversified developer exposure is structurally safer than single-issuer corporate bonds.
- Vietnam's anticipated FTSE market upgrade may widen legitimate capital market access for the stronger players. That story is worth monitoring if you want Vietnam fixed income exposure with better institutional backing.
Bottom line: high-yield bonds from distressed developers are not a savings vehicle. They are a credit bet with illiquid collateral in a sector where 70% of delayed obligations sit. Price the risk accordingly, or park your capital somewhere that lets you sleep.
Around the Region
⚡ Quick Hits
🇹🇭 Thailand (Isan): Three cities, three completely different markets.Northeastern Thailand is bifurcating sharply. Khon Kaen saw condominium sales surge 70% on urban employment growth. Udon Thani recorded a 719.8% jump in new project launches, pushing unsold inventory up 74.6%, creating serious medium-term absorption pressure. Korat (Nakhon Ratchasima) sits with a 51-month housing clearance horizon. These markets look nothing like each other. Investing in "Isan" as a category rather than a specific city is a category error.
🇲🇾 Malaysia: The institutional money is going to logistics, not luxury condominiums.Malaysian investment sales reached RM3.58 billion across 33 deals in early 2026, with the dominant theme being industrial and logistics assets. Institutional capital is betting on supply chain resilience and e-commerce fulfilment over residential towers in Johor. The Johor residential story remains valid for lifestyle buyers and Singapore proximity plays, but the hot commercial money is pointing a different direction.
🇮🇩 Indonesia: Danantara makes its first property move. Indonesia's newly established sovereign investment entity, Danantara, offered 360,000 property units at a national exposition to stimulate institutional liquidity. This is the government signalling it is willing to use sovereign capital to stabilise the residential pipeline at scale. Whether it shifts the affordability dial meaningfully is another question, but it confirms state-level attention is firmly on the housing gap. Worth tracking for anyone looking at large-format Indonesian residential projects.
🇻🇳 Vietnam: Apartment lifespan rules could redefine how central city properties are valued.Upcoming statutory amendments aim to separate the physical depreciation of a building from its underlying perpetual land-use rights. In plain terms: a central Hanoi apartment in a 40-year-old block would retain its land-use value even if the building is scheduled for redevelopment. This is potentially significant for buyers of older central urban stock in Vietnam, and worth monitoring as the legislation moves through the National Assembly.
Numbers Worth Knowing
📊 Yield Snapshot and Market Data
| Market | Metric | Figure |
|---|---|---|
| Singapore (OCR) | Private home price change (Q3 2026) | +2.2% QoQ |
| Singapore (CCR) | Prime home price change (Q3 2026) | -0.1% QoQ |
| Bangkok (Sukhumvit) | Condo monthly absorption rate | 5.2% (16-mo clearance) |
| Bangkok (low-rise) | Unsold inventory clearance horizon | 67 months |
| Thailand (nationwide) | New condo launch forecast (full-year 2026) | ~17,000 units (20-yr low) |
| Vietnam (real estate bonds) | Corporate bond coupon range (Oct 2026) | 12.0% to 13.5% |
| Vietnam | Share of delayed corporate debt from real estate | >70% |
| Jakarta (landed vs vertical) | Price-to-income multiples | 22x vs 8.8x |
| Phuket (Rhea by Sansiri) | Estimated net rental yield range | 3.2% to 4.3% |
| Malaysia (institutional) | Investment sales volume (early 2026) | RM3.58 billion (33 deals) |
Caution: Yield figures reflect current market estimates. Always calculate net of costs: management fees, maintenance levies, vacancy allowances, and platform commissions. The 3 to 5% gross yields marketed on many Phuket condotel projects typically land at 1.5 to 2.5% net after operational costs. Net is the only number that matters for your cashflow model.
🏠 STR Investor Corner
October Is When Resort Market Pricing Gets Rebuilt for the Season. Do It Now.
If you own a short-term rental in Phuket, Bali, Koh Samui, or any resort market with a November to April peak season, October is not a slow month to wait out. It is the month to rebuild your pricing architecture for peak season. What you do now determines your Q1 2027 numbers. Most operators get this backwards: they wait until November to set peak pricing, by which point the early bookers (who pay full rate without flinching) have already gone to competitors who were ready.
Three things to do in October before peak bookings lock in:
1. Audit your competitive set
Pull up the top 10 comparable listings in your area and check what they charged last November, December, and January. Your dynamic pricing floor for peak season should sit at or above the median, not at the low end of your comp set. If you lock in early bookings at undermarket rates, you cannot recover without cancelling accepted reservations.
2. Price the Christmas to New Year window separately
December 20 to January 5 is not regular peak season. It commands a 40 to 70% premium over standard December rates in most resort markets. Block this window separately in your channel manager and price it independently. Do not let your base algorithm apply the same rate as December 15 or January 10.
3. Set flexible minimum stay rules by sub-period
A 7-night minimum during Christmas week prevents fragmented gaps that cannot be filled at the last minute. A 3-night minimum in late January, when demand softens, can be the difference between 80% and 60% occupancy. Build this flexibility into your calendar now, before early bookings lock in the wrong pattern.
The operators who fill peak calendars first are rarely the cheapest. They are the ones who price with confidence in October, hold their rates through November, and let the late-booking market pay full rate in December. Build for that outcome.
🏡 Looking at a deal in Southeast Asia? Let us help.
Our team tracks active inventory across Thailand, Malaysia, Singapore, Indonesia, Vietnam, Cambodia, and the Philippines. Whether you are evaluating a specific project or mapping a broader strategy, we can help you cut through the noise.
Final Thought
🤔 The Market Is Not Broken. It Is Bifurcating.
Every few months a data point lands that makes Southeast Asian property sound like it is on the verge of collapse. Vietnam bonds at 13.5%. Thai mortgage rejections at 50%. Jakarta homes at 22 times income. These are real numbers and they are worth taking seriously. But they describe one end of a market that is running two completely different stories simultaneously.
The stressed end is domestically leveraged, mass-market, and caught between rising developer funding costs and shrinking buyer access to bank credit. This is genuinely difficult for a lot of people, and we do not minimise it. But the foreign capital end of the same markets is watching a different film. Bangkok transit condominiums are absorbing in under 20 months. Phuket's foreign buyer mix is shifting and deepening. Singapore suburban prices keep finding new floors despite volume contraction. Institutional capital in Malaysia is deploying into logistics at a pace that suggests conviction, not caution.
The bifurcation is the story. Cross-border investors with hard currency and a 3-to-5-year hold horizon are in a fundamentally different position than domestic buyers squeezed by bank rejection rates and developer balance sheet risk. Knowing which story you are in is half the strategy. The other half is identifying the specific assets that are correctly priced within it. That is what the Hawook platform is built to help you do. Prior issues are archived at news.hawook.co. We will see you next week.
The Hawook Weekly
hawook.com | news.hawook.co | app.hawook.com
This newsletter is for informational purposes only and does not constitute financial, legal, or investment advice. Property markets involve risk. Always conduct your own due diligence and consult qualified advisors before making investment decisions. Hawook does not guarantee the accuracy or completeness of third-party data cited in this publication. Unsubscribe or manage preferences via your Beehiiv settings.